House flip earnest money deposit: how buyers fund, protect, and recover EMD
Earnest money is the buyer good-faith deposit that makes a house flip contract real. This guide shows United States residential investors what the deposit is, who should hold it, when it can be refunded or forfeited, how inspection and financing contingencies interact with the money, how to avoid wire fraud, and how three named investor examples keep the file organized through close.
Written and reviewed by the Rehabfolio editorial team. Published and last reviewed September 21, 2026.
Who this guide is for. This guide is for beginner and early United States residential investors buying a one-to-four-unit house they intend to renovate and resell. It starts when you write a purchase offer and ends when the earnest money is credited at closing, returned under a written contract path, or disputed after a missed deadline. If you are still setting a walk-away price, begin with the 70% rule and maximum offer guide. If the contract is already signed and you are verifying the house, use the house flip due diligence checklist. If you are later selling the finished flip, deposit language on incoming buyer offers belongs in how to compare house flip offers and the seller closing checklist.
The Rehabfolio editorial team builds and reviews product workflows that connect property analyses, purchase files, deposit dates, inspection notes, repair scopes, budgets, tasks, photos, and closing records. That gives the team first-hand product experience organizing a buyer deposit beside contingencies and settlement credits. It does not make the team a broker, real-estate licensee, attorney, escrow or title professional, lender, inspector, appraiser, insurer, accountant, tax adviser, or investment adviser.
Purchase-contract forms, escrow rules, notice methods, refund timing, and forfeiture remedies differ by state, locality, property type, occupancy, and the exact form you sign. This guide is educational information, not legal, brokerage, escrow, lending, tax, or investment advice. Use the signed contract and licensed local professionals for the house in front of you.
Tip: Keep this earnest money guide beside first-property analysis, pipeline stages, due diligence, hard money comparison, holding costs, and change orders so the deposit, the inspection clock, the loan file, and later renovation changes do not get treated as one pile of cash.
1. Define earnest money versus option money, lender deposits, and seller credits
Beginners often treat every check that leaves the checking account as the same deposit. They are not. Mixing the purchase-contract earnest money with a lender good-faith fee, an option fee, or a later seller credit is how investors lose track of which dollars are at risk if they cancel, and which dollars were never in the seller escrow at all.
- Earnest money deposit (EMD) is the buyer good-faith sum named in the purchase contract. A third party holds it. If the sale closes, it is usually credited toward the price or cash to close. The National Association of REALTORS consumer guide on escrow and earnest money describes it as a deposit that shows the buyer intends to close, held securely until closing or until a dispute is resolved.
- Option money appears on some state forms. The Texas Real Estate Commission explains that, on its revised residential contracts, the buyer delivers an option fee to the title company, the fee may be combined with earnest money, funds are applied first to the option fee, and the escrow agent may release the option fee to the seller. That option fee pays for an unrestricted right to terminate during a written option period. It is a different legal pot from refundable earnest money, and it is not a national default.
- Hard-money or private-lender deposits are loan-file money: application deposits, commitment fees, or construction reserves. They live in the lending relationship described in hard money loan offers. They do not substitute for the seller-side earnest money escrow.
- Seller credits are concessions the seller agrees to pay or credit at closing. They change net proceeds and cash to close. They are not the buyer deposit. Offer-comparison work on the sale side belongs in compare house flip offers.
Keep four evidence types separate while you write the offer. Observed facts are the signed form, the named holder, the dated receipt, and the settlement line that later shows the deposit. Calculations convert a percentage or a fixed sum into cash you must wire this week, plus any additional deposit due later. Assumptions cover local custom about size and whether a seller will accept a small fixed amount. Opinions describe how "strong" the offer feels. "Title Company A receipted $7,500 on Tuesday" is a fact. "We are covered because we wired something" is an opinion that fails when the holder, amount, or deadline was wrong.
2. Read typical amounts as custom, not advice
No federal statute sets a house flip earnest money number. The NAR consumer guide states there are no laws requiring an earnest money deposit on a home offer, that deposits are common practice, and that amounts may be a percentage of price or a set figure. That same educational page describes typical ranges from about 1 percent to 10 percent of purchase price, notes that fixed amounts are becoming more common in some regions, and lists competitiveness, down payment size, contingencies, and seller preference as factors. Those are consumer-education ranges. They are not Rehabfolio pricing, not a license requirement, and not a recommendation for your house.
House flip buyers often see three illustrative patterns. A first deal in a calmer listing market may use a modest fixed sum, such as $2,000 to $10,000 on a mid-six-figure contract, because the seller wants proof of funds more than a large hostage deposit. A competitive cash or short-inspection offer may use a larger fixed sum or a higher percentage because the seller is comparing certainty. A two-step contract may name an initial deposit due in a few days and an additional deposit due after inspections. Those examples are teaching composites. Your broker or attorney should tell you what local listing agents actually expect this month.
Size the deposit beside the rest of the offer math, not in isolation. A large EMD does not fix a price that fails the walk-away screen. A tiny EMD with a long inspection window can look weak next to another buyer who wrote a clearer diligence plan. Model the cash that must sit in escrow through the inspection window as part of holding-cost arithmetic, because that money is unavailable for materials or contractor deposits until it is credited or returned.
AI tools may help you list deposit percentages against a few recent local contracts you already have in the file. A person still decides the number, because custom, seller motivation, and your risk tolerance are not a model output. Keep the language provider-neutral: organize examples, label them as illustrations, and require human approval before the offer is sent.
3. Name who holds escrow and how delivery works
NAR's escrow and earnest money consumer guide describes escrow as a third-party arrangement in which an attorney, settlement agent, or similar professional controls funds and releases them only when contract terms are met. That is the job you want. The buyer and the seller should not be able to spend the deposit while the contract is alive.
Write four holder facts into the offer before anyone asks for a wire:
- Legal name of the escrow holder. Title company, closing attorney, or broker escrow. Not "send it to the listing agent's personal account."
- Delivery method the holder actually accepts. Wired good funds, cashier's check, or another method the escrow instructions name. Some holders will not treat a personal check as good funds until it clears.
- Delivery deadline. Many forms count a short number of days from the effective date. Some extend a weekend or legal-holiday deadline to the next business day. Count the way the form counts, including the hour if the form states one.
- Receipt path. Who emails the receipt, what it must show (amount, file number, property address), and where you store it beside the contract.
Texas TREC educational material is a useful state example, not a national rule. TREC explains that buyers deliver the option fee to the title company within three days after the effective date, that earnest money and option fee may be combined, and that received funds are applied first to the option fee. If you are not using that form family, do not import those deadlines. If you are using that form family, read the current contract and TREC article rather than this paragraph.
On a financed consumer purchase, the deposit later appears as a credit. The Consumer Financial Protection Bureau closing-disclosure explainer groups the deposit with amounts already paid by or on behalf of the borrower, separate from cash to close. Older HUD-1 settlement statements used a line labeled "Deposit or earnest money." Cash investors may receive a different settlement statement, but the same idea applies: the deposit should reduce cash due, not vanish. Confirm the line at the closing table even when you are the buyer, because a missing credit is a file error you can still catch.
4. Connect contingencies to refund and forfeiture paths
Earnest money becomes risky when the contract rights that protect it expire. The inspection window in the due diligence checklist is the most common buyer protection on a flip. Financing, appraisal, title, survey, insurance bindability, and lead-based paint opportunities can also create written exit ramps. None of those ramps work if you only think about canceling. The form usually requires a written notice, a method, and a clock.
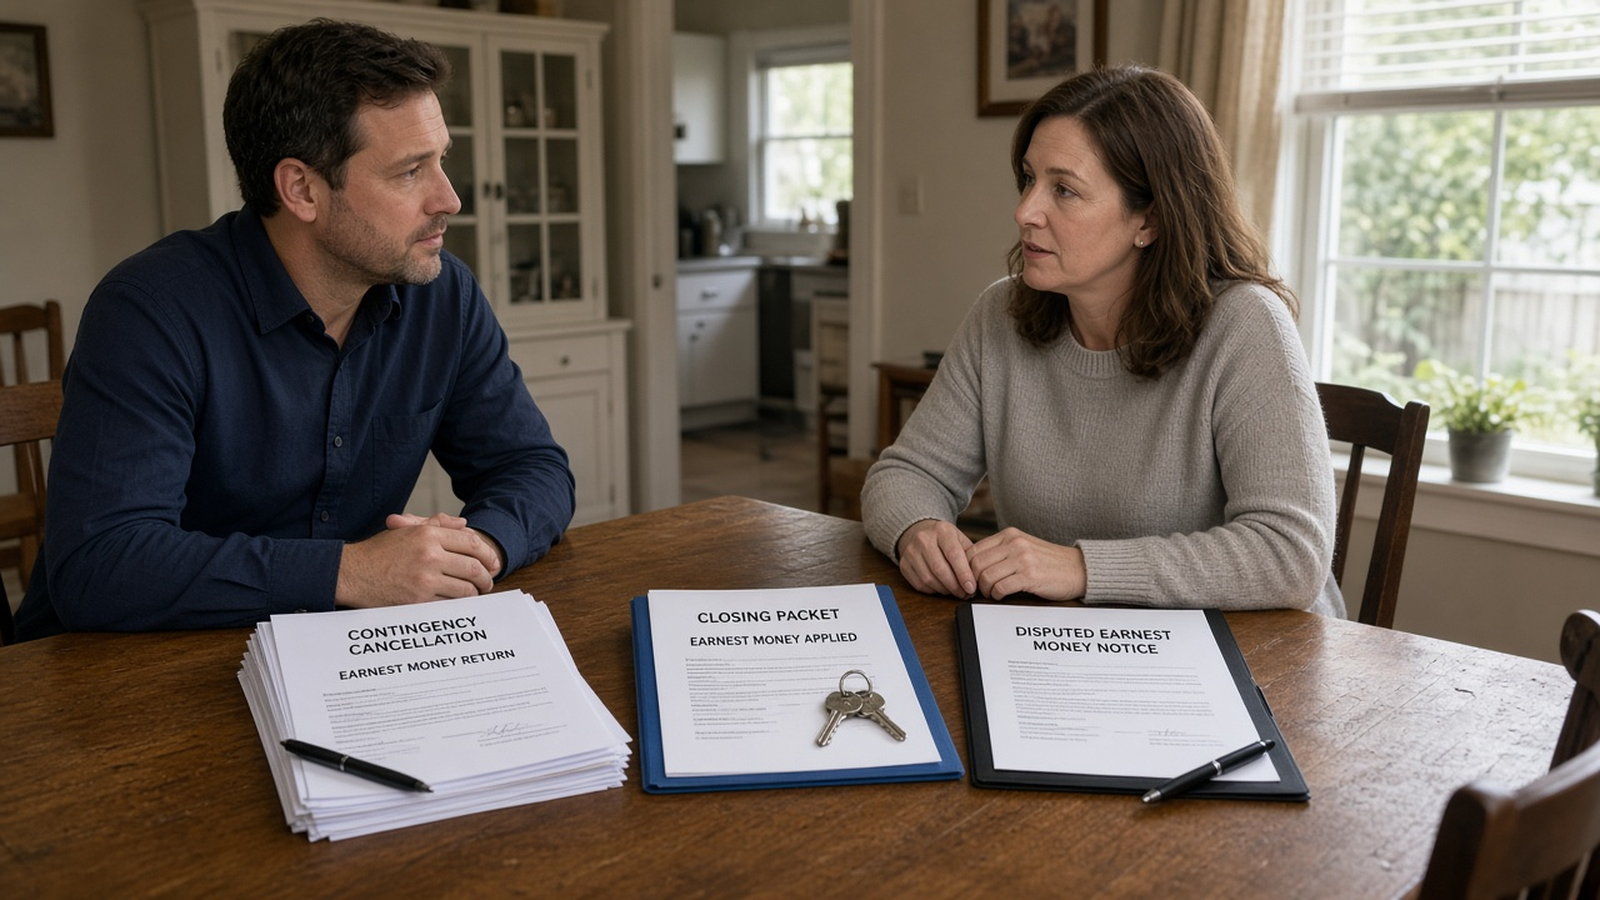
Treat the deposit as following one of three educational paths:
- Cancel under a live contingency or option. You still have a written right. You give notice the way the contract requires, before the deadline. Escrow then follows the release language. Refunds are often not instant. The holder may wait for a signed release or for funds to finish clearing.
- Close the purchase. Contingencies are removed or expire as agreed. The deposit is credited on the settlement statement. You should see it as money already paid, not as a second stack you bring again.
- Missed notice or buyer default. The deadline passes, or you fail to perform after protections expire. Many forms let the seller claim the deposit as liquidated damages. That claim is not the same as an automatic wire to the seller. Escrow companies often need a mutual release, a court order, or an interpleader if the parties disagree.
Inspection and financing interact with the deposit in different ways. An inspection contingency is usually about condition evidence and a rebuilt repair budget. A financing contingency is about whether the loan you described can actually fund. Cash flip offers often waive financing and keep a short inspection right. That can make the deposit more exposed after the inspection clock ends. Hard-money approval letters are not a substitute for reading whether your purchase form still has a financing out.
Removing contingencies is a written event. A verbal "we are moving forward" to the listing agent is not a safe substitute for the form the contract names. After removal, later renovation surprises are change-order and contingency-budget problems, not automatic deposit refunds. See change orders once you own the house. Do not try to use earnest money theater to paper over a scope you already accepted.
5. Protect the wire before any funds leave the bank
Earnest money and closing funds are a known target for criminals who impersonate title companies, attorneys, and agents. The CFPB has warned that scammers send last-minute wiring-instruction changes that divert closing costs and related funds. NAR's consumer guide on real estate wire fraud tells buyers to confirm instructions with a number obtained independently, not from the suspicious email. The Federal Trade Commission's consumer advice on wiring money stresses that wires are hard to reverse and that pressure to send money immediately is a warning sign.
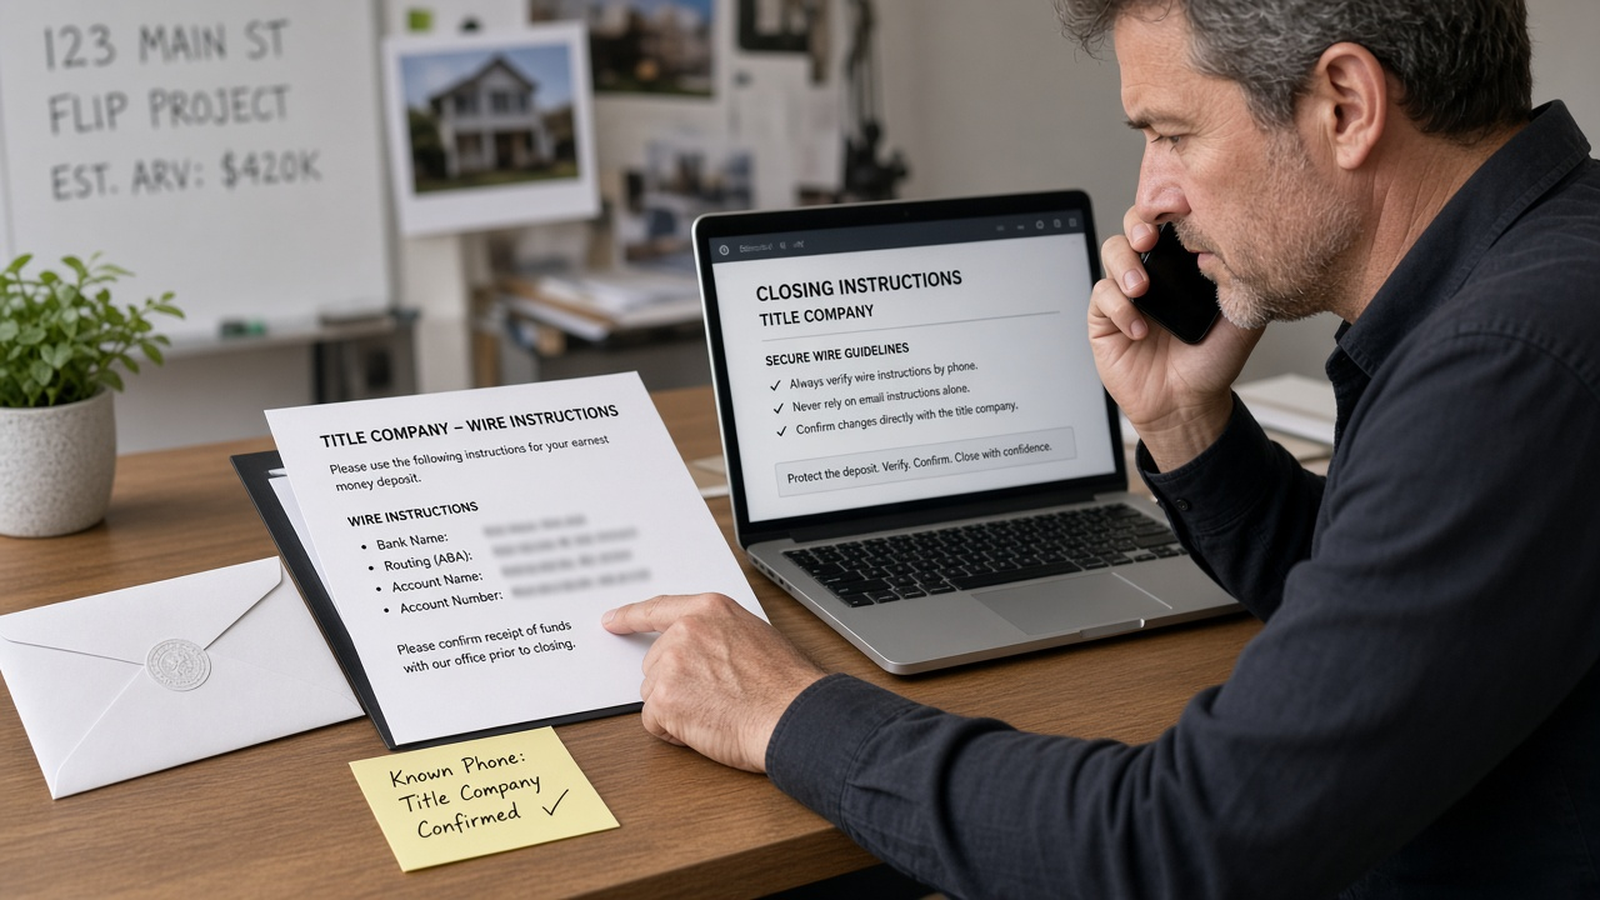
- Name the holder in the signed contract before anyone sends instructions.
- Collect a phone number you already trust from the office card, the company website you typed yourself, or an in-person closing preview. Do not use the number in a surprise email.
- Call and read the account name, bank, and amount out loud on that known number, even the first time you wire.
- Refuse emailed changes. A "new account because the other one is under audit" story is a classic fraud pattern. Start over with the known number.
- Send only the contract amount to the named beneficiary. Extra verification wires and new last-minute payees are not part of a normal EMD delivery.
- Act the same hour if something looks wrong. Ask your bank for a wire recall. Then report through official channels such as ReportFraud.ftc.gov and the FBI Internet Crime Complaint Center.
This checklist is consumer-protection hygiene. It is not a guarantee you will recover a stolen wire. Title companies, banks, and law enforcement control those next steps. Rehabfolio can store the verified holder name and the receipt. It cannot send the wire or certify that an account is safe.
6. Track release, refund timing, and dispute paths
Investors often assume a canceled contract means an automatic refund the next morning. Escrow is slower and more formal than that. The holder follows the written instructions. If those instructions require both parties to sign a release, a seller who disagrees can stall the refund even when you believe you canceled on time. If the holder is unsure who should receive the funds, some companies file an interpleader and let a court or later settlement decide.
Build a release file the day you decide to cancel or close:
- The signed purchase contract and every amendment.
- Proof the deposit was delivered (receipt, wire confirmation).
- The contingency or option paragraph you are using.
- The written notice, sent by the method and time the form requires.
- Delivery proof (email timestamp, portal receipt, or courier record).
- The release form the escrow holder uses, if they require one.
- A calendar note for follow-up if the refund has not posted.
Refund timing is local practice. Some holders return funds a few business days after a clean release. Others wait for deposited checks to clear or for a supervisor review. Do not spend the expected refund on materials until it actually lands. If you are closing instead of canceling, compare the Deposit line on the closing disclosure or settlement statement with your receipt before you wire the remaining cash to close.
Forfeiture is a legal claim, not a mood. A seller who says "you wasted my time, so the money is mine" still has to fit the contract remedies. Do not negotiate that claim by text without counsel. Do not sign a release that gives the seller the deposit if you believe you canceled under a live contingency, unless you intend that outcome. Keep the file, then ask a licensed attorney in that state how the form treats liquidated damages, specific performance, and release language.
7. Build the buyer deposit documentation checklist
A clean deposit file does not win the house by itself. A messy file is how buyers miss a deadline, wire the wrong account, or cannot prove they canceled on time. Assemble the same packet on every offer.
- Offer math first. Walk-away price, repair budget, and hold from property analysis before you pick a deposit that you cannot afford to have tied up.
- Contract deposit paragraph. Amount, additional amount if any, holder legal name, delivery method, and deadline.
- Contingency calendar. Inspection, financing, appraisal, title, lead, option, and notice-hour rules, counted the way the form counts.
- Verified wire or check instructions. Confirmed on a known phone number. Printed or saved with the name of the person who confirmed.
- Delivery receipt. Amount, file number, property address, date, and holder name.
- Diligence workpapers. Inspector booking, access notes, and the rebuilt budget that will decide keep, amend, or cancel. See due diligence.
- Decision notice draft. Prepared before the last day so you are not inventing language at 4:50 p.m.
- Closing-credit check. Deposit line on the settlement statement matches the receipt.
Pipeline hygiene matters when you have more than one offer out. The four-stage pipeline should show which deals have live deposits, which clocks expire this week, and which refunds are still outstanding so you do not double-commit the same cash.
8. Work three named investor scenarios
The following stories are original educational composites. Names, streets, prices, and outcomes are invented for teaching. They are not testimonials, client results, or promises about refunds.
Scenario A: Elena Voss cancels inside a live inspection window and recovers the deposit. Elena is buying a 1974 three-bedroom in Lansing, Michigan, under a $218,000 contract. She writes a $4,000 earnest money deposit (about 1.8 percent of price) to a named title company, due two business days after the effective date. The form gives her a ten-day inspection contingency and requires written notice before 5:00 p.m. local time on day ten. Elena wires $4,000 after calling the title office on the number from the company website she typed herself. She receives a receipt the same afternoon. On day six a sewer scope shows a collapsed run that rebuilds her repair budget by $19,000 and breaks her walk-away number from the offer screen. On day eight she sends the contract cancel notice through the method the form names, copies the title file, and asks for the holder's release form. Both parties sign the release on day twelve. The title company returns $4,000 on day sixteen. The lesson is not the dollar amount. The lesson is that a named holder, a dated receipt, and a notice sent before the written hour kept the refund path usable.
Scenario B: Marcus Bell misses the notice hour and faces a forfeiture claim. Marcus writes a $12,000 earnest money deposit on a $265,000 vacant ranch in suburban Atlanta because three other investors are circling. He keeps a five-day inspection window and no financing contingency. The inspector finds unpermitted electrical work on day four. Marcus tells the listing agent by text that he is "probably out" and starts pricing another house. He does not send the written notice the form requires. Day five ends. On day six the seller's agent cites the missed deadline and asks the escrow holder to release $12,000 as liquidated damages. The holder refuses to send money to anyone without a mutual release. Marcus now has a dispute file, not a refund. He hires a Georgia real-estate attorney, who explains that the text was not the notice the form demanded. After two weeks the parties sign a split release as a negotiated settlement. That split is an example of dispute friction, not a rule. Missing the written clock turned a diligence cancel into a deposit fight.
Scenario C: Aisha Rahman separates option money, earnest money, and a lender deposit. Aisha is underwriting a Houston bungalow using a TREC-style residential contract as a teaching example. The offer names $5,000 earnest money and a $250 option fee, both payable to the title company within three days, with funds applied first to the option fee as TREC educational material describes. She also pays her hard-money lender a $1,500 loan-file deposit that is not part of the seller escrow. During a seven-day option period she finds flood insurance will not bind on terms she can hold. She terminates under the option paragraph. The option fee is not refunded. The $5,000 earnest money follows the contract refund path after the required notice. The lender later refunds part of the unused loan-file deposit under the loan agreement, on a different clock. Aisha logs three receipts in three folders so nobody treats $6,750 as one "deposit." The scenario shows why option money, purchase earnest money, and lender deposits must stay labeled as separate pots.
9. Follow one complete earnest money cycle
Baseline property. Theo Park is buying a 1962 cape in Worcester, Massachusetts, for $241,000. After-repair value after selling costs supports about $330,000. Repairs are underwritten at $46,000. Holding cost is modeled at $62 per day. Walk-away profit target is $22,000. Theo writes $6,000 earnest money (about 2.5 percent of price) to Harbor Street Title, due three calendar days after the effective date, with a ten-day inspection contingency and a financing contingency tied to a hard-money term sheet.
Delivery and confirmation. On day one Theo calls Harbor Street Title on the number from the office card collected at the listing preview. The closer reads back the account name and file number. Theo wires $6,000 and saves the confirmation plus the emailed receipt. A later email claiming "updated wiring instructions for the additional deposit" is ignored after the same closer says no additional deposit exists and no account changed. That near-miss never becomes a second wire.
Diligence decision. The general inspection and a roof estimate raise repairs from $46,000 to $51,500. The deal still clears the walk-away number. Theo sends a written repair request. The seller refuses repairs and offers no credit. Theo decides to proceed anyway, then removes the inspection contingency in the form the contract names on day nine. The hard-money lender issues a clear-to-close after appraisal. Theo removes financing in writing. The $6,000 remains in escrow.
Closing credit. On the settlement statement the deposit appears as $6,000 already paid. Cash to close is reduced by that amount. Theo compares the line with the title receipt before wiring the remaining funds, again on a known phone number. After closing, the earnest money is no longer a separate risk. Later kitchen tile changes are renovation change orders, paid from project cash, not from a deposit that already became a price credit.
Opinion versus fact. Theo likes the listing agent's communication style. That opinion does not confirm a wire account, does not extend a missed notice hour, and does not replace the Deposit line on the settlement statement.
10. A repeatable Rehabfolio earnest money workflow
- Finish offer math first. Price, repairs, hold, and walk-away before you pick a deposit size.
- Write the deposit paragraph in full. Amount, additional amount, holder, method, deadline.
- Build the contingency calendar. Inspection, financing, title, option, and notice hours.
- Verify the holder on a known phone number. Then deliver good funds and store the receipt.
- Run diligence against the rebuilt budget. Decide keep, amend, or cancel while rights are live.
- Send written notices on time. Use the contract method. Keep proof of delivery.
- Close the money loop. Confirm the settlement credit, or chase the release and refund until the bank shows it.
- Archive the chain. Contract, receipt, notices, release, and settlement page stay with the project.
Rehabfolio can help you organize those deal documents, deposit amounts, holder names, timelines, receipts, and closing notes in one workspace. It cannot hold escrow, send wires, give legal advice, interpret a state form, or decide how large the deposit should be. Connect the record to the fix-and-flip workflow so the same project that stores the underwrite also stores the money that made the contract real.
AI tools may help draft a deadline checklist from a contract PDF or flag a missing receipt filename. A person still verifies the holder, the amount, the notice language, and whether you should cancel. Keep the process provider-neutral: evidence visible, assumptions labeled, human approval before money moves.
Frequently asked questions
What is a house flip earnest money deposit?
Earnest money is a buyer good-faith deposit named in the purchase contract. A neutral escrow holder, often a title company, closing attorney, or broker trust account, keeps the funds until the sale closes, the parties sign a release, or a contract path says the money is refunded or forfeited. It is not the down payment, not a lender construction deposit, and not a seller credit.
How much earnest money is typical on a house flip?
There is no national legal amount. Consumer education from the National Association of REALTORS notes that deposits are commonly a percentage of price or a fixed dollar figure, and that published ranges such as about 1 percent to 10 percent are market custom, not a statute. Competitive investor offers sometimes use a larger fixed sum. Treat every range in this guide as illustrative. Your contract, local custom, and counsel control the number you actually write.
Who holds the earnest money, and when do I deliver it?
The purchase contract should name the escrow holder and the delivery deadline. In many markets that holder is a title or escrow company. In attorney-closing states it may be a closing attorney trust account. Some brokerages still use a broker escrow account where state rules allow it. Delivery is often due within a short number of business days after the effective date. Get a dated receipt. Do not send funds to a personal account or to new wiring instructions that arrived only by email.
When does earnest money become nonrefundable?
Refundability is a contract question. While a written inspection, financing, appraisal, title, or option right is still live, a timely cancel in the required form can preserve a refund path. After those rights expire, after you remove contingencies in writing, or after you miss a notice deadline, the seller may have a claim to the deposit if the form treats it as liquidated damages. Even then, many escrow holders will not release funds to anyone without a written release, a contract instruction they can follow, or a later legal process.
How is earnest money different from option money or a hard-money deposit?
Earnest money sits in the purchase-contract escrow and is usually credited if you close. Option money, used on some state forms such as the Texas Real Estate Commission residential contract family, pays for an unrestricted termination option and is often released to the seller and not refunded if you cancel. A hard-money or private-lender deposit is money the lender requires for the loan file. It is a different pot, a different receipt, and a different refund rule. Seller credits are concessions against price or closing costs. They are not the buyer deposit.
How do I avoid losing the deposit to wire fraud?
Name the holder in the contract. Collect the office phone number in person or from a directory you already trust. Treat any emailed change to wiring instructions as hostile until you confirm the account name, bank, and amount out loud on that known number. Send only the contract amount. Keep the receipt. If a wire looks wrong, call your bank the same hour and ask for a recall, then report through official fraud channels such as the FTC and the FBI Internet Crime Complaint Center.
Can Rehabfolio hold my earnest money or tell me how much to deposit?
No. Rehabfolio can help you organize the purchase contract, deposit amount, holder name, delivery deadline, receipts, contingency dates, notices, and closing-credit notes in one project record. It cannot hold escrow, send or receive wires, give legal advice, interpret your state form, or decide the deposit amount. Use the named escrow holder, your broker or attorney, and qualified local professionals for those decisions.
Editorial methodology, limitations, and sources
The Rehabfolio editorial team chose this topic as a distinct buy-side purchase-contract earnest money workflow for house flips. It does not replace the inspection-window intent of the due diligence guide, the walk-away math of the 70 percent rule guide, the sale-side deposit comparison in the offer comparison guide, the seller closing checklist, or later renovation change-order control. Those guides remain the homes for condition verification, offer screens, incoming buyer deposits, seller settlement, and post-purchase scope changes. This guide focuses on what the buyer deposit is, how it is delivered and held, when it is credited, refunded, or fought over, and how it differs from option money, lender deposits, and seller credits.
Key sources include the National Association of REALTORS Consumer Guide: Escrow and Earnest Money on third-party escrow, good-faith deposits, and educational amount ranges; the Consumer Financial Protection Bureau Closing Disclosure explainer showing the deposit as an amount already paid toward cash to close; the CFPB mortgage closing scams guidance on last-minute wiring-instruction fraud; NAR Consumer Guide: How to Protect Against Real Estate Wire Fraud; the Federal Trade Commission What To Know Before You Wire Money; the Texas Real Estate Commission article Changes to Delivery of Option Fee as a state-form example of option money versus earnest money; and the CFPB HUD-1 settlement statement explainer showing the older "Deposit or earnest money" credit line. Local brokers, escrow holders, and real-estate counsel remain necessary for one property. National consumer pages cannot set your deposit or release your escrow.
Public guidance cannot tell you whether $5,000 or $15,000 is the right number, whether a particular seller will sign a release, or whether a missed notice still leaves a refund path in your state. Examples are original composites created for teaching. Names, addresses, figures, and outcomes are illustrative, not testimonials or performance claims. Percentages and dollar figures are educational, not quotes or guaranteed refund results.
Editorial standard. We identify the audience, author, review date, topic boundary, assumptions, calculations, product evidence, and limitations. We do not invent credentials, licenses, testimonials, market statistics, or guaranteed results. AI may help organize research and draft, and a person reviews the claims, calculations, links, examples, and limitations before publication. We revise the guide when a cited rule, product workflow, or material escrow practice changes. See the editorial methodology on the company page.
Keep deposit amounts, escrow receipts, and contingency dates in one clear project record.
Organize the contract, the wire receipt, the inspection clock, and the closing credit without pretending software can hold escrow or decide the deposit.
Create free account